Depreciating business assets
You do not book a business asset of €450 or more as a cost in one go. You spread the cost over the years you use it. This is called depreciation (afschrijven). (Belastingdienst: depreciation)
The calculation
You need three figures:
- the purchase cost: the price without deductible VAT, including non-deductible VAT;
- the residual value: what the asset is still worth at the end;
- the useful life: how many years you expect to use it.
The depreciation per year is (purchase cost − residual value) divided by the useful life. (Belastingdienst: amount of depreciation)
Maximum 20% per year
The depreciation is at most 20% of the purchase cost per year. So you depreciate an asset over at least 5 years.
Example
You buy a laptop for €1,500 without VAT. The residual value is €0. You expect to use it for 5 years. You then depreciate €300 per year.
The first year
Do you buy the asset during the year? Then in that year you depreciate in proportion to the months you had it.
No depreciation
You do not depreciate land. Separate rules apply to a business premises.
In ZZPboek
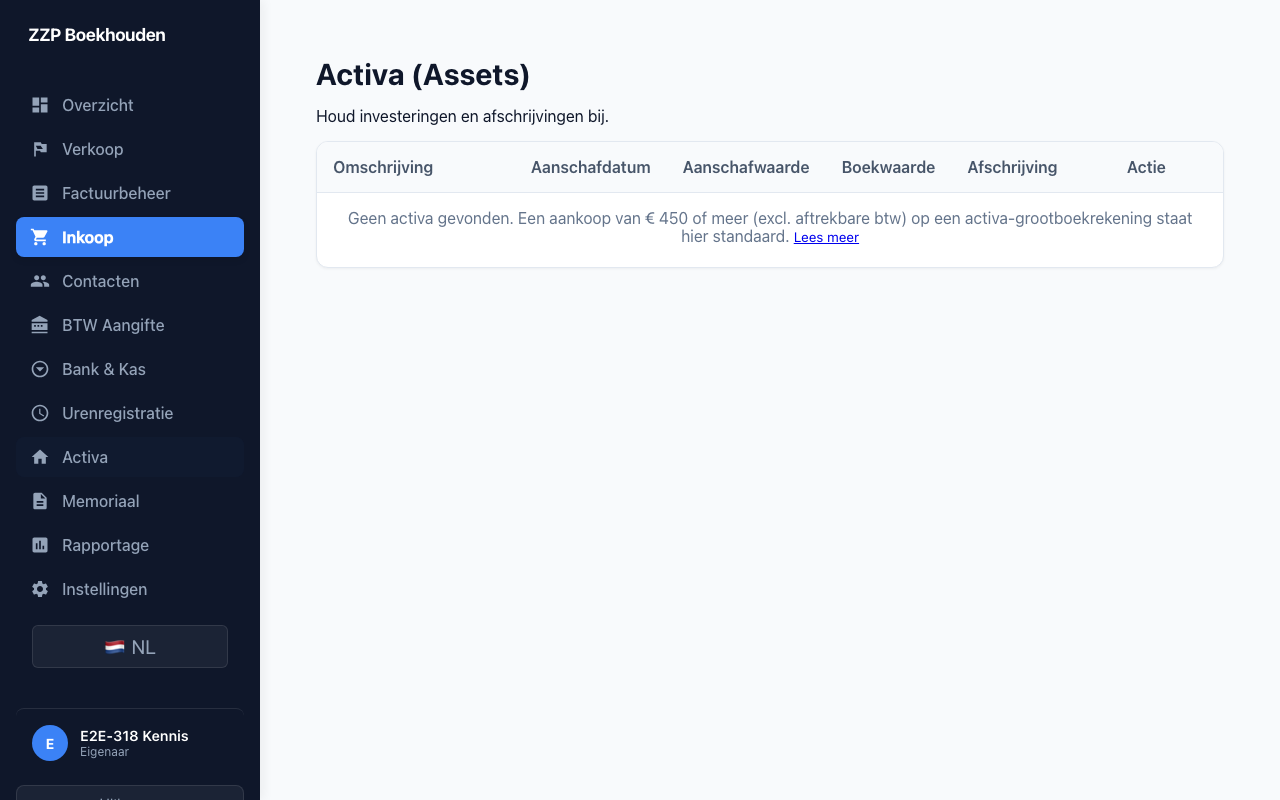
For each fixed asset you see the purchase price, the residual value, the useful life and the book value. The app books the depreciation per month and shows it in your profit and loss account.
Sources
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/winst/inkomstenbelasting/inkomstenbelasting_voor_ondernemers/afschrijving/hoe_berekent_u_het_bedrag_van_de_afschrijving
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/winst/inkomstenbelasting/inkomstenbelasting_voor_ondernemers/afschrijving/
This article is general information, not tax advice. If you are unsure about your situation, ask the Belastingdienst or an adviser.