Draft: this article is still being reviewed.
Reverse-charged VAT: box 2a, 4a and 4b
With reverse-charged VAT, the supplier charges no VAT. The customer, so you, declares the VAT yourself in the return. (Belastingdienst: how VAT reverse charge works)
Recognising it
The invoice says "btw verlegd" or "reverse charge". There is no VAT amount on it. Your business's VAT number is often on it.
Which box?
- 2a: the supplier is in the Netherlands and the VAT has been reverse-charged to you, for example in construction subcontracting.
- 4a: the supplier is outside the EU, for example a software service from the United States or the United Kingdom. (Belastingdienst: services from suppliers in non-EU countries)
- 4b: the supplier is in another EU country. You declare the total and the VAT in 4b. (Belastingdienst: goods and services from other EU countries)
Paying and deducting
You calculate the VAT at the Dutch rate, usually 21%. You put that VAT in 2a, 4a or 4b. Do you use the purchase for your VAT-taxed revenue? Then you deduct the same amount in 5b. Net, you then pay nothing. You do have to fill in both.
No reverse charge
Is there foreign VAT on the invoice? Then the VAT is not reverse-charged. You do not deduct that foreign VAT in your Dutch return. You claim it back from the supplier's country.
In ZZPboek
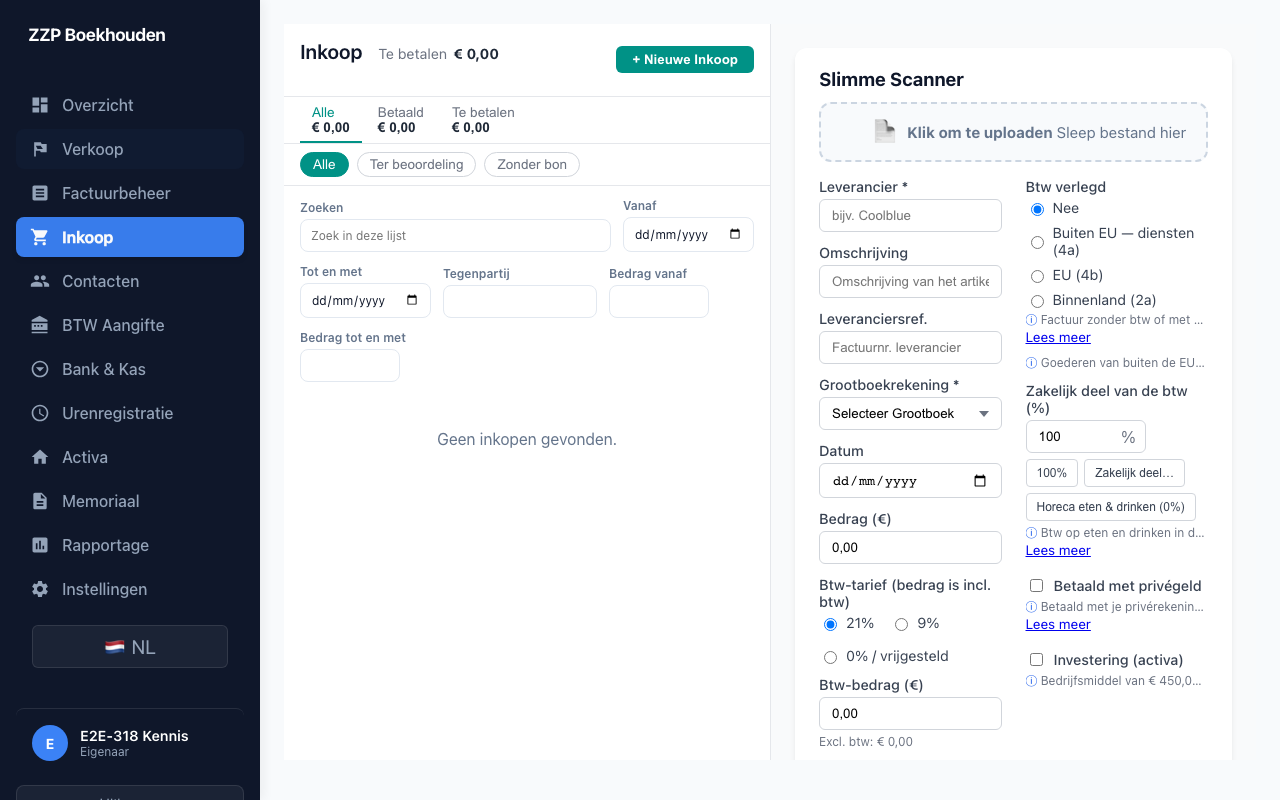
For a purchase you choose 2a, 4a or 4b under "btw verlegd" (reverse-charged VAT). The app calculates the VAT and puts it in the box and in 5b. Not sure? The explanation at the field says which box belongs to which supplier.
Sources
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/btw/btw_berekenen_aan_uw_klanten/waarover_btw_berekenen/verleggingsregeling/hoe_werkt_btw_verleggen
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/btw/zakendoen_met_het_buitenland/goederen_en_diensten_afnemen_uit_andere_eu_landen/aangifte_doen/aangifte-doen-van-goederen-en-diensten-uit-andere-eu-landen
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/btw/zakendoen_met_het_buitenland/zakendoen_buiten_de_eu/aangifte_doen_als_u_zakendoet_buiten_de_eu/aangifte_doen_als_u_diensten_afneemt_van_leveranciers_uit_niet_eu_landen
This article is general information, not tax advice. If you are unsure about your situation, ask the Belastingdienst or an adviser.