Draft: this article is still being reviewed.
Hospitality and mixed costs
Food and drink in a restaurant or café is a business expense for many freelancers. Separate rules apply for VAT and for income tax.
VAT: not deductible
You cannot deduct VAT on food and drink that you consume at a hospitality venue. This also applies if you take a client along. The Belastingdienst treats spending on yourself as private spending. (Belastingdienst: hospitality spending)
Income tax: gemengde kosten (mixed costs)
Food, drink, entertainment and conferences are mixed costs. Only part of them is deductible from your profit. You choose one of two methods. (Belastingdienst: threshold for partly deductible costs 2026)
- Threshold: the first part of the yearly total is not deductible. In 2026 the threshold is €5,700.
- 80% rule: you deduct 80% of these costs.
For low amounts, the 80% rule is almost always more favourable. You make the choice in your income tax return.
Groceries and your own kitchen
Do you buy coffee or biscuits for your office? That is not hospitality. The VAT on that purchase is then usually deductible.
In ZZPboek
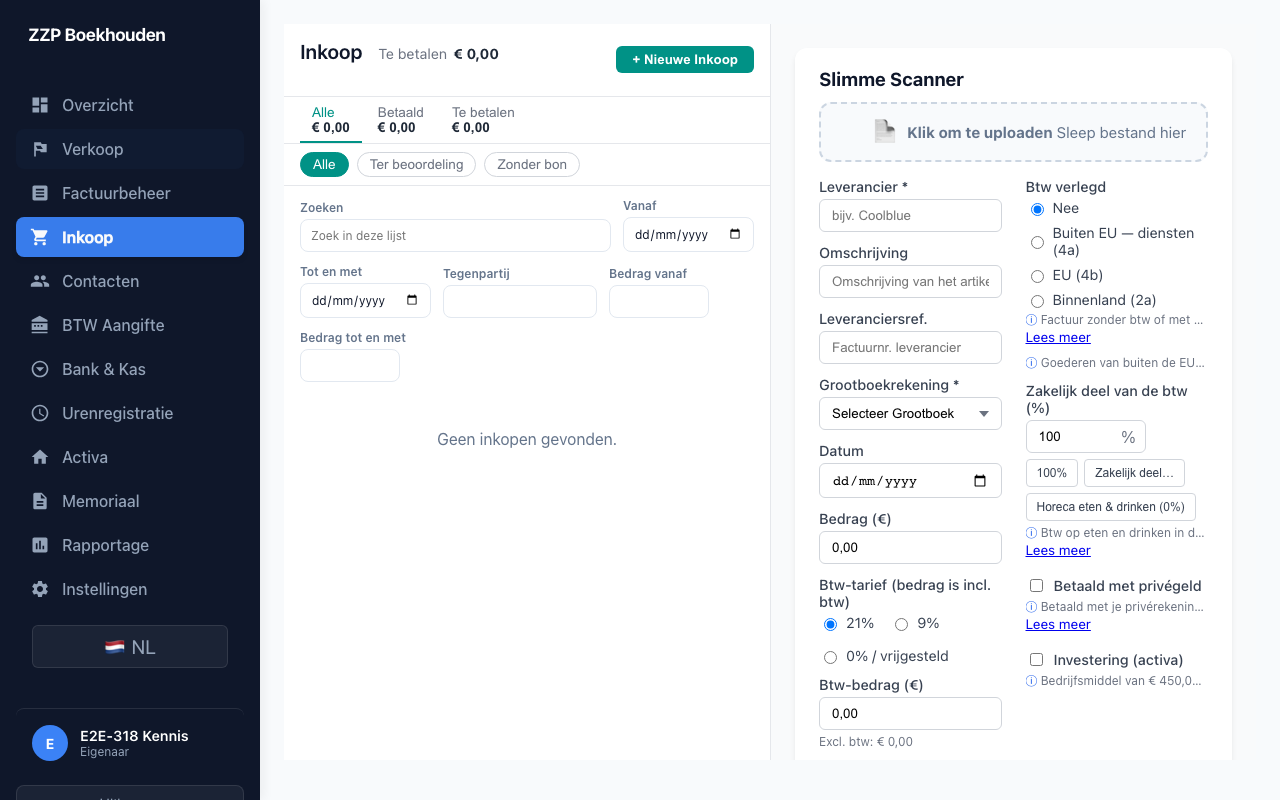
For a purchase, choose the account for hospitality or entertainment. The app then does not put the VAT in box (rubriek) 5b, but counts it as a cost. In the tax estimate, the app uses the more favourable of the two rules.
Sources
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/btw/btw_aftrekken/welke_btw_is_aftrekbaar/bijzondere_situaties/uitgaven_in_de_horeca
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/winst/inkomstenbelasting/veranderingen-inkomstenbelasting-2026/drempel-beperkt-aftrekbare-kosten-2026
This article is general information, not tax advice. If you are unsure about your situation, ask the Belastingdienst or an adviser.