Private use of business items
As a freelancer, you use many items for both business and private purposes. Your phone, your laptop or your car. Then you must decide which part is for business.
VAT: only the business part
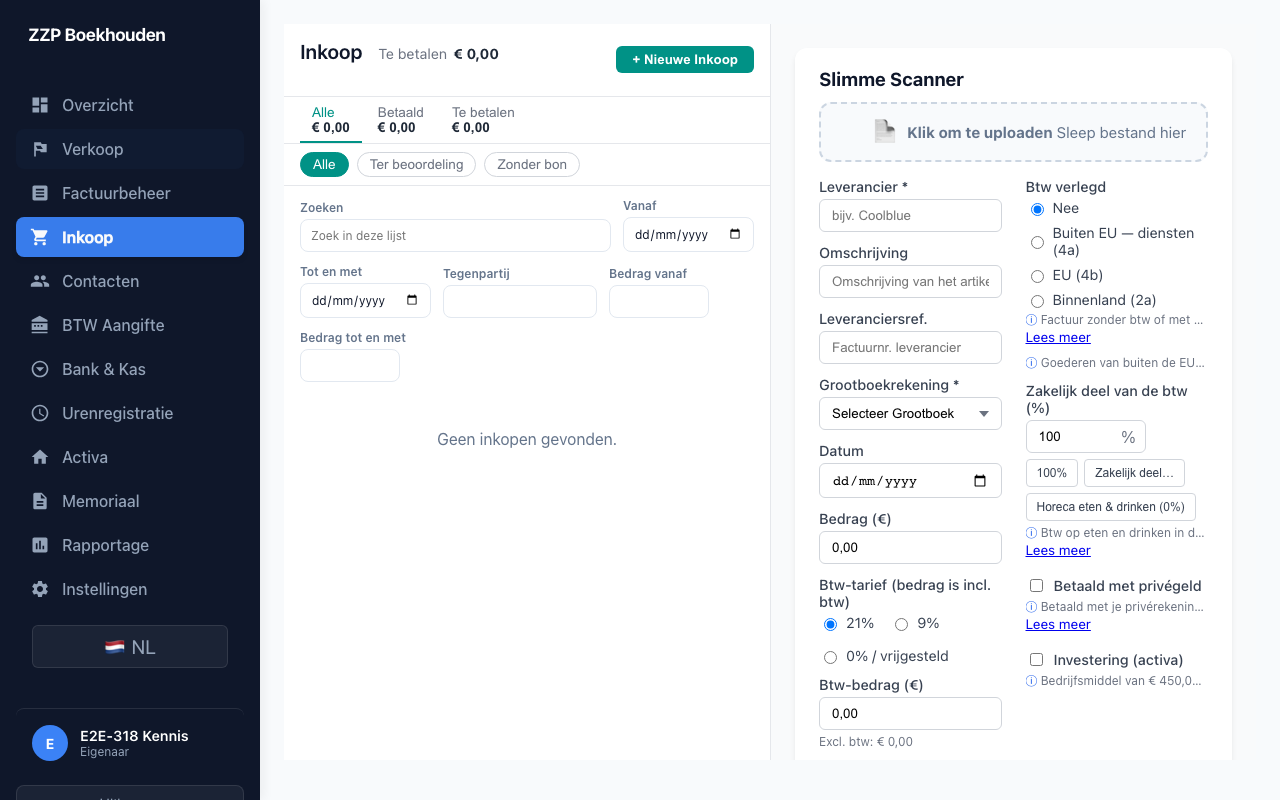
You deduct VAT only for the part that you use for business. If you use your phone 70% for business, you deduct 70% of the VAT.
Later only private
Do you start using something you bought for the business only privately? Then you pay VAT on that private use. Is the item still unused and does it move to private use within a year of buying it? Then you pay VAT on the original purchase price. (Belastingdienst: exclusively private use)
For a movable capital good (roerend investeringsgoed) the herziening (revision) also applies. You follow the purchase in the year you start using it and the 4 years after: the revision period (herzieningsperiode). Do you use it (partly) privately in those years? Then you pay VAT for that private use. (Belastingdienst: movable capital goods)
Capital goods
Extra rules apply to more expensive items that you also use privately. You can allocate them fully to your business, and then you correct the VAT for the private use. (Belastingdienst: whole business assets)
Your own car or bike for business
Do you use your private car for your business? Then in 2026 you can deduct €0.25 per business kilometre from your profit. In 2025 this was €0.23. (Belastingdienst: business use of a private vehicle 2026)
A company car
A company car that you also use privately has its own rules for VAT and income tax. Read them on the Belastingdienst pages before you buy the car.
In ZZPboek
For a purchase, you enter the business part of the VAT, for example 70%. The app deducts only that part in box (rubriek) 5b. You record business kilometres with your own car in the hours overview.
Sources
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/btw/btw_aftrekken/privegebruik/uitsluitend_privegebruik
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/btw/btw_aftrekken/privegebruik/gemengd_gebruik/investeringsgoederen/roerende_investeringsgoederen/roerende_investeringsgoederen
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/btw/btw_aftrekken/privegebruik/gemengd_gebruik/investeringsgoederen/geheel_bedrijfsvermogen
- https://www.belastingdienst.nl/wps/wcm/connect/bldcontentnl/belastingdienst/zakelijk/winst/inkomstenbelasting/veranderingen-inkomstenbelasting-2026/zakelijk-gebruik-privevervoermiddel-2026
This article is general information, not tax advice. If you are unsure about your situation, ask the Belastingdienst or an adviser.